
Welcome back to another monthly update from Root of Good! We spent most of April at home enjoying the springtime flora and fauna. But we also managed to squeeze in a week in the Caribbean on board the Holland America Rotterdam cruise ship.
Right now we are just a few days away from commencing a six week period of busy travel that brings us to the west coast of the USA, then Alaska, Europe, and at the end of June, back to the Caribbean. We’ll be back home for a few days here and there but mostly on the road during that timeframe.
I’ve spent a big part of April taking care of “business” at home. Working on financial planning and filing taxes, tackling some chores and repairs around the house, and visiting with family and friends. Since we’re doing a lot of traveling, I’ve been doing a lot of research and travel planning as well. I’m basically a part-time travel agent these days (with a customer base of one very demanding client – me!).
On to our financial progress. April was a decent month for our finances overall. Our net worth increased very slightly by $4,000 to end the month at $3,351,000. Our April income of $3,581 was almost enough to cover our spending of $4,261 for the month.
Let’s jump into the details from last month.
Income
Investment income totaled $868 in April. Our equity index funds and ETFs pay dividends quarterly at the end of March, June, September, and December. As a result, we had a smaller than normal amount of investment income last month. Here’s more on our dividend investments.
Blog income totaled $360 for the month. This represents an average month of blog income.
My early retirement lifestyle consulting income (“consulting”) was $1,156 last month. This represents six hours of consulting. I’m very happy with the last two months of $1,000+ in revenue from consulting. During April I had a technical hiccup with my email and website server for several weeks so it appears I may have lost out on a client or two that contacted me. So far May is starting off well, but I anticipate lower revenues for May and June because I will not be as available to conduct consulting sessions.
Tradeline sales income totaled $250 last month. This is a bit lower than recent months but I know the exact amount will fluctuate month-to-month. I ramped up my tradeline sales a few years ago and discussed it in a bit more detail in my October 2020 monthly post and in my July 2021 monthly post. During 2024 I made over $6,000 in exchange for lending out my stellar credit history from half a dozen credit cards.
For last month, my “deposit income” totaled $50. Of that total, $10 was due to cash back and incentive bonuses from the Rakuten.com and Mrrebates.com online shopping portals (some of which was earned from you readers signing up through these links).
If you sign up for Rakuten through this link and make a qualifying $25 purchase through Rakuten, you’ll get a $10 sign up bonus (or more!).
The other $40 in deposit income was a class action settlement check from a lawsuit against Facebook because… Well they breached my rights in some very egregious manner I am sure, and I feel like $40 is more than fair compensation for my injuries!
My bank and credit card bonuses totaled $895 last month. I signed up for a US Bank Business Leverage card and received a $750 sign up bonus plus another $145 from the 2% cash back on the spending I put on the card.

If you’re interested in tracking your income and expenses like I do, then check out Empower Personal Dashboard, formerly known as Personal Capital (it’s free!). All of our savings and spending accounts (including checking, money market, and more than half a dozen credit cards) are all linked and updated in real time through Empower Personal Dashboard. We have accounts all over the place, and Empower Personal Dashboard makes it really easy to check on everything at one time.
Empower Personal Dashboard is also a solid tool for investment management. Keeping track of our entire investment portfolio takes two clicks. If you haven’t signed up for the free Empower Personal Dashboard service, check it out today (review here).
Tracking spending was one of the critical steps I took that allowed me to retire at 33. And it’s now easier than ever with Empower Personal Dashboard.
Expenses
Now let’s take a look at April expenses:

In total, we spent $4,261 during the month of April which is about $1,000 more than our regularly budgeted $3,333 per month (or $40,000 per year). Healthcare/medical and travel were the two largest categories from last month.
Detailed breakdown of spending:
Healthcare/Medical/Dental – $1,827:
Our 2025 health insurance is free thanks to very generous Affordable Care Act subsidies that we receive due to our low ~$51,000 per year Adjusted Gross Income.
Our 2025 dental insurance plan normally costs $32 in premiums per month. We picked a plan from Truassure through the healthcare.gov exchange. The dental insurance does a good job of covering most of our routine cleanings, exams, and x-rays plus most of the cost of basic procedures like fillings. I paid $19 during April which is less than the normal monthly charge because the insurance company messed up the billing earlier during 2025.
We had several dental visits and procedures completed during the month of April totaling $1,817. That’s after insurance paid for a portion of the procedures. Dental care remains the most expensive part of our health/medical expenses. We have one more similarly large payment during May or June and then hopefully our dental expenses drop back down close to $0 for the remainder of the year.


Travel – $857:
Last month’s travel spending was a mix of several different expenses.
I spent $99 on the annual fee for a new American Airlines credit card. The sign up bonus on that card earned us 70,000 American Aadvantage miles which is more than enough to pay for a round trip flight to Europe.
Another small charge was the $8 in convenience fees I paid so that I could use a credit card to pay my $400 quarterly estimated taxes for the State of North Carolina.
The largest part of our travel spending during April came from travel arrangements to get to Europe for a couple of upcoming cruises.
- taxes for four “free” one-way award flights home from Europe: $400
- 2x United Kingdom ETA visas (which aren’t “really” visas but they still cost money): $26
- Round trip train tickets from London to the coast for two: $98
Other April travel expenses included incidental expenses for our weeklong Caribbean cruise. We spent $31 for Uber/Lyfts between the Ft. Lauderdale Airport and the cruise port in Ft. Lauderdale. Included in that total is a $10 discount for using my Chase Sapphire Reserve Card for the Lyft ride. While onboard, we spent $195 on the mandatory gratuities plus some small purchases in the gift shop.
Get free travel like us
If you are interested in getting free travel from your credit card like I do, consider the Chase Ink Preferred business card (my referral link). Right now, the Chase Ink Preferred business card offers an above average $900 worth of Chase Ultimate Rewards points that can be redeemed instantly for $900 in cash (or even more for travel!). I just signed up for another new Ink card to snag one of these great bonus offers.
Chase is pretty liberal when it comes to “what is a business”. If you sell stuff on eBay or Craigslist or do some odd jobs occasionally then you have a business and could get a credit card as a “sole proprietor”.
I use the 90,000 Chase Ultimate Rewards points by transferring them to my Chase Sapphire Reserve card (also offering a 60,000 point sign up bonus right now). With the Sapphire Reserve card, I can get 1.5x the points value by booking cruises, flights, hotels, or rental cars through their travel portal. For example, I used 165,000 Chase Ultimate Reward points to pay for the $2,475 in taxes, fees, and gratuities on two of my cruises. Or I can transfer those Ultimate rewards points to over a dozen travel partners’ airline/hotel programs like United, Southwest, or Hyatt.


Capital One VentureX card
Another favorite travel card in my wallet is the Capital One Venture X card. The Venture X card is a “keeper” for me. First off, it comes with a $750 sign up bonus after spending $4,000 in the first three months. The bonus is paid in the form of 75,000 bonus points that you can redeem against any travel purchases from anywhere. Then you earn a solid 2 points per dollar spent forever! The other big perk is airport lounge access. You can get yourself plus unlimited guests into Priority Pass lounges. And you and two of your guests can get into Plaza Premium network lounges and Capital One Lounges.
The Capital One Venture X card does have one catch – a $395 annual fee. But they reward you every year with an easy to use $300 travel discount plus $100 worth of points. Together, that makes $400 they give you annually which completely offsets the annual fee. Another benefit worth mentioning: you can add up to four authorized users for free, and they also get all the benefits of the Venture X card including the valuable airport lounge access. We used this perk to “gift” a pair of Venture X cards with airport lounge access to my brother in law and his wife to use on their family trip back home to Cambodia last April with their two young children.
Since the annual fee is offset in full by travel credits each year, I personally plan on keeping the Venture X card forever since the card benefits are so great.
Groceries – $789:
We spent $789 on groceries last month. This represents a pretty normal month of groceries for us. Inflation on food is way up over the past few years, so the days of a $500 or $600 monthly grocery bill are long gone (at least while our kids are still living with us).

Taxes – $415:
I paid our North Carolina quarterly estimated tax bill of $400 during April. The other $15 in tax expense came from the $15 FreeTaxesUSA fee to file my state income tax online.
Utilities – $247:
We spent $139 on our water/sewer/trash bill last month.
The electric bill was $108 last month. We had to use the air conditioning a small amount during the April billing period and that usage will increase as we proceed through the warmer spring and summer months.
There was no April natural gas bill because I paid it in full during the last few days of March.
Gas – $50:
Two tanks of gas for our Hyundai Accent for $50 total. Through the end of April, our daughter had to drive to the NC State University campus about 7 miles away. Now that summer is here, she’s finishing up her degree with a few online courses so she won’t be driving nearly as much. The main car usage is back to running errands and social outings or vacations for us.

Clothing/Shoes – $29:
A visit to the thrift shop for some new (or “new to us”) clothes.
Cable/Satellite/Internet – $25:
We usually pay $25 per month for a local reduced rate package due to having a lower income and having kids. 50 mbit/s download, 10 mbit/s upload.
Restaurants – $17:
Mrs. Root of Good went out to lunch with her friends last month for $17.
Automotive – $7:
The windshield wiper spray nozzle on top of the hood stopped working last month. When I went to inspect it, the plastic nozzle fragmented into several pieces. For $7, I found a replacement nozzle on ebay that was easy to install and it’s working fine now and only took a few minutes to install.


Spending for 2025 – Year to Date

We spent $13,948 for the first four months of 2025. This annual spending is slightly over our budgeted $13,333 for four months per our $40,000 annual early retirement budget. I haven’t increased our annual budget for inflation in a decade, so at some point I need to revisit the budget numbers.
We aren’t really trying to be super frugal these days, so if the spending comes in higher than our budget, that’s okay.

Right now we are continuing our plan to spend weeks at a time traveling all over the world. During the remainder of 2025, we’ll be spending eight weeks cruising around Alaska, Scotland, Ireland, and the Baltic Sea while visiting dozens of ports along the way. We also have two cruises booked with our kids during the summer. And to wrap up the year, we’re doing a cruise through the Panama Canal from Fort Lauderdale to the west coast of the USA. Between all that travel, some down time in Raleigh, and a few holidays and special events, we’re just about booked up for 2025.
However I’m already looking at interesting trip ideas for 2026, and won’t hesitate to spend some money on more trips for next year. But hopefully I can do some travel hacking to keep the out of pocket expenses to a minimum.
In May, we have our annual home insurance bill and our six-month auto insurance bill due, which will be about $2,500 in total. Plus some more dental expenses. It’s looking like another month of big spending. Will we end up back on budget at some point during the summer? Who knows!

Monthly Expense Summary for 2025:
- January – $5,091
- February – $2,462
- March – $2,136
- April – $4,261
Summary of annual spending from more than a decade of my early retirement:
- 2014 – $34,352
- 2015 – $23,802
- 2016 – $38,991
- 2017 – $31,708
- 2018 – $29,058
- 2019 – $25,630
- 2020 – $28,466
- 2021 – $31,740
- 2022 – $29,449
- 2023 – $37,865
- 2024 – $40,286
- 2025 – $13,948 (through 4/30/2025)
Net Worth: $3,351,000 (+$4,000)
Our net worth increased slightly by $4,000 to end the month at $3,351,000.
The last two months we’ve experienced a $14,000 drop in March and a $4,000 gain in April. Not exactly the roller coaster that you see portrayed in the media, when you look at our month to month investment returns instead of daily numbers. And in reality, monthly numbers are meaningless too. I just include them in here for entertainment purposes so there’s filler text between all the vacation and animal pictures.

For the curious, our net worth reported above includes our home value (which is fully paid off). I value the house at $300,000, which is probably what we would net after sales expenses. However, please note that I don’t consider my home value as part of my portfolio for “4% rule” calculation purposes. I realize folks ask me about that every month so I just wanted to state that here for clarity.

Closing thoughts
Big changes coming up? Or not?
Our oldest two kids graduate from college this year. One daughter just graduated (congrats!) and our other daughter completes her degree at the end of July. They are still searching for jobs and have no imminent plans to move out. Our son, the youngest child, still has several more years of K-12 education so he’ll be at home for a while.
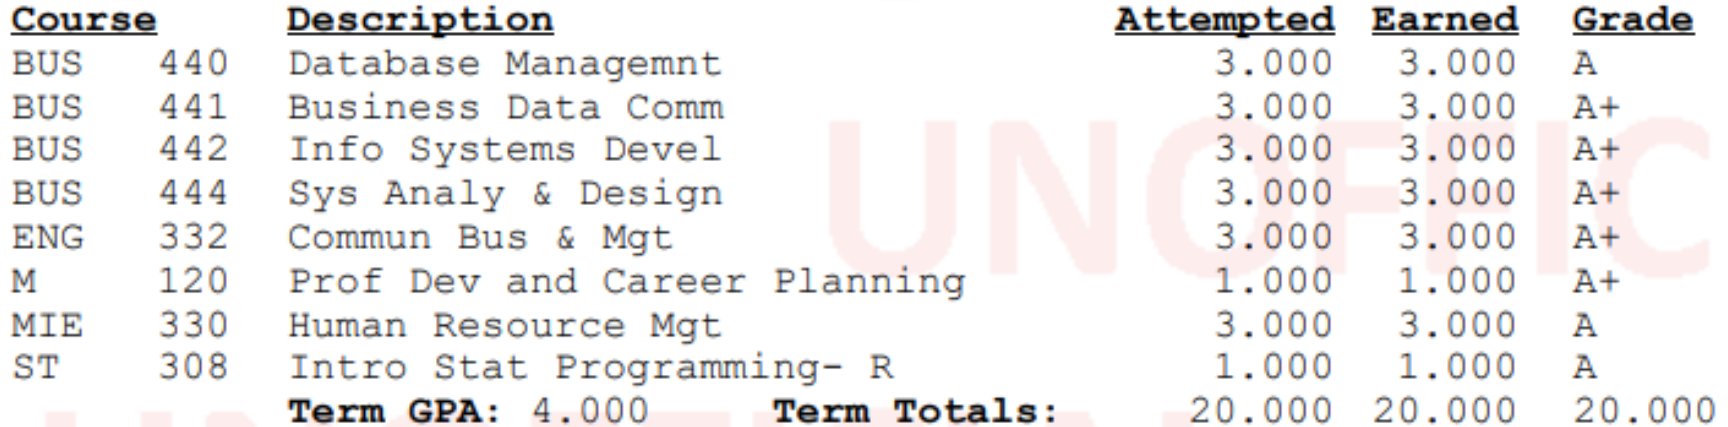
We went ahead and made summer travel plans based on guesses about when our older two kids would have school or jobs and not be able to travel with us. They will both find jobs eventually but right now they don’t have any real leads.
Hopefully the job market picks up for them. In the meantime it’s nice to have them around. We enjoy them being full time house sitters and providing rides to the airport.
Well that’s it for me this month. I’ll be traveling till mid-June so the next monthly update will be delayed quite a bit. See you next time!
Who is looking forward to summertime?
Want to get the latest posts from Root of Good? Make sure to subscribe on Facebook, Twitter, or by email (in the box at the top of the page) or RSS feed reader.
Root of Good Recommends:
- Empower Personal Finance Dashboard* - It's the best FREE way to track your spending, income, and entire investment portfolio all in one place. Did I mention it's FREE?
- Interactive Brokers $1,000 bonus* - Get a $1,000 bonus when you transfer $300,000 to Interactive Brokers zero fee brokerage account. For transfers under $300,000 get a 0.333% bonus on whatever you transfer
- $750+ bonus with a new business credit card from Chase* - We score $10,000 worth of free travel every year from credit card sign up bonuses. Get your free travel, too.
- Use a shopping portal like Ebates* and save more on everything you buy online. Get a $10 bonus* when you sign up now.
- Google Fi* - Use the link and save $20 on unlimited calls and texts for US cell service plus 200+ countries of free international coverage. Only $20 per month plus $10 per GB data.
Discover more from Root of Good
Subscribe to get the latest posts sent to your email.
Our spending was up more than usual the last month too! Health and it had been 5 years since we got summer tires on our vehicle. Wildlife mecca in your back yard! Love it. Thanks for sharing.
Medical bills and new tires – not even that much fun to spend $ on that 🙂
Thanks for the update, sounds like life is good. Congrats on your daughter’s accomplishments and thanks for posting her grades, that was a nice way to end this month’s post. Safe travels.
Thank you!
Congrats on the two college graduates!! Very impressive grades you shared. Do you have any theories on why the job market is “soft” for new grads like your two? We keep telling our kids to get a college degree but fear it may be a waste of $
I think the job market is a bit soft but not bad (yet anyway!). Seems like it started to weaken 6-8 months ago. More recently, I think fear of trade shocks led to pessimism among management and reluctance to hire more people, not knowing which way the economy is going. Hopefully a short term phenomenon and we get back to good economic times soon.
I think college is still a good bet **if** you don’t spend a ton on expensive colleges and you pick the right majors that will lead to a career that actually pays well. $250k for a four year degree that lets you earn $40-50k/yr is a horrible value proposition versus just starting work somewhere and working hard at what you do and moving up. Or learning some skilled trade at a community college 1 year program. Doesn’t have to be hard work blue collar stuff. Lots of medical/dental field jobs that pay decent too.
I always enjoy reading your monthly posts…they are so inspiring. Have fun traveling this summer, and congrats to the college grads!
Thanks!
Okay how did Mrs RoG have a $17 lunch out! I assume she and friends do not split check evenly?
Could you share more about your socializing expenses? Going to each other’s houses exclusively or something else? Weekend dinners with friends seem to run us back at least $100 every weekend. Thanks!
It was a “fast casual” restaurant but it’s pretty good. Jason’s Deli, I think they are a chain with locations throughout parts of the USA. She tips which adds a bit (I don’t remember tipping when I used to go there often when I worked next door but maybe the service format changed?). Her friends probably all spend about the same, maybe a bit more with a drink. I guess they all pay separately at the counter (if the format is still like it was 15-20 years ago when I’d visit there)
For social events, I host at my house mostly. Coffee on the back porch or campfires, that kind of thing. Have also met up for walks/bike rides or at a park. I hadn’t really thought about it but I don’t go out to eat that much with friends. Maybe too many frugal friends will do that to you 🙂
If the ACA subsidies and TCJA cuts are allowed to expire in 2026, how will these changes affect your monthly expenses?
I think ACA reverts to pre-covid levels so max of 9.5% of your income goes toward health insurance. For me, it will likely be <$100 extra, all else being equal. However we may have 1-2 kids that are no longer tax dependents either this year or next year so we may pay more for health insurance because of that.
Have you switched over to Holland America from MSC? Or maybe using both now? Good luck with your summer plans….sounds like an awesome adventure.
Both lines for now. We have a couple Holland America cruises coming up but also an MSC cruise.
Congratulations on having concluded some amazing trips, Justin. And congratulations to your daughters as well for their graduation milestone. I am sure they will do well in life; after all, they had some parents who did so and no reason they won’t do the same.
Summertime is our time of the year to stay in TN and enjoy everything our state has to offer, before we also hit the cruising and travel stage in the late Fall and all of Winter. We have gotten some decent deals on Carnival cruises ourselves and am hoping those accelerate more if they hit a snag with lower #s of people booking. Right now that is iffy since people seem to have glommed onto the fun of cruising, and most cruise lines are seeing record bookings.
As for your investments, I am pretty confident that the worst of the news is over on the tariff front, and any negative consequences are already baked into the market. From now on we should see a fairly steady drip upwards as more and more trade deals are announced. Best wishes on that front since we (and I assume most other people) are almost back to recovering everything since the absolute low point a month or so back. Life is good.
We’ll be home in Raleigh for almost a whole month in July! I’m kind of afraid of the heat since we are rarely here. It’s tempting to go somewhere cooler but I’m also looking forward to a “vacation” at home ha ha ha
I think you’re right on the market and trade shock fears. I don’t know what we’ll end up with but if we can get some stability that will let businesses go back to making money and plan around whatever the new foreign trade policies are.
Congratulations on your two daughters graduating from college!
Thank you thank you!!
Your daughter rocks! Back in my day, NCSU didn’t have the +/- system and it was hard enough getting A’s. Getting that many A+’s is really hard.
I think they started the A+’s in the very late 90’s?? That’s when I started and for some reason I think my year might have been some of the first to have the A+’s.
I wonder how this will affect you:
“ACA tax credits and other financial incentives, implemented by the Biden administration in 2021, are scheduled to expire next year leading to higher premium costs for people who enroll through the federal healthcare marketplace.”
https://www.upi.com/Top_News/US/2025/05/04/1-million-amricans-to-oose-insurace-aetna-leaves-marketplace/8431746402394/
Would other insurance companies follow Aetna in leavings the ACA program?
(This reminds me of auto insurance companies leaving the state of Florida.)
Without the ACA we will be forced to self insure and/or do without healthcare, much like we did prior to the ACA.
I haven’t had a chance to research fully since I’ve been on vacation lately. But this appears to be just a reversion to pre-pandemic ACA subsidies. We all pay a little more; some folks that can’t get their AGI to be what they want it might lose coverage.
Aetna leaving the ACA exchange probably won’t mean much to me personally. We have 4-5 insurers in my zip code in North Carolina so having only 3-4 just means I pick a different one. I was with Aetna for 2 years then switched to a different insurer this year. The way the ACA subsidies work is the 2nd lowest cost silver plan determines the subsidy amount. So if costs go up due to less competition, then we just get a bigger subsidy.
Sure, there’s a risk that most or all insurers leave the marketplace but I can’t imagine that would happen if we just revert back to 2020 era ACA policy.
Have you been to Greece ? If so, which area did you visit ??
I haven’t been to Greece unfortunately but would like to visit! From what I’ve researched, I’d visit a few islands and probably some greek ruins on the mainland. And visit outside of the summer months to avoid crowds, high prices and unbearable heat.
Wow, that is one hard working and smart daughter! Congratulations to her, and tell her to hang in there on the job search. Once management can predict future costs reliably again (i.e. tariff changing on whims), then hiring will return to previous levels. I can attest to that as a business owner of a small tech company.
I’m amazed and inspired by the life you’re living, and the relentless growth of your portfolio. I took a look at the difference slices of your Asset Allocation post. Have you maintained this allocation since 2013, and have you ever compared it to just owning VTI/VXUS? Obviously, it’s worked out for you, but I was just curious if you wished you had simplified or changed anything? I am very close to pulling chocks myself – largely because of the inspiration I’m drawing from you.
Yeah fingers crossed we get some stability in the market and on tariffs so we hiring managers and owners can get back to growing the economy!
As far as asset allocation, not much has changed for me since 2013. I added a 10% slice of bonds in 2016-2017 time frame but otherwise the equity portion is still sliced and diced as in my Asset Allocation post. In hindsight, I’d of course pick a total US market index for 100% of my portfolio because the return was higher! For my kids and other folks that need a simple portfolio, I’ve been buying VT which is the Total World index.
Congratulation to your two new college graduates. It is a very real accomplishment and I know they have done well. It is also a nice gateway to the next stage of their life. I wish them the best in the job market.
Thanks! Very exciting times over here!
This is such a helpful post! I am still on my journey to financial freedom but am getting closer by the month… seeing how you’re living and spending is eye-opening.
Thanks for sharing the exact numbers and specific ways you’re doing it. It’s so helpful for planning purposes.
Thanks,
Matt
You are welcome, and best of luck on your journey!
Are you still getting the discounted negotiated in-network rates on all these dental procedures that aren’t covered by the insurance?
Sometimes they do still give us the negotiated rates. I don’t think the dentist has to, but we’ve been patients there for almost 2 decades now so I guess he cuts us some slack sometimes.
How you not succumb to the urge of spending more???? buying a better modern car? travel more luxuriously?? or just go out to eat more when you know you have the money to do so and life time gets shorter and shorter?
Magic? Not sure really.
AS it is now we spend about 4-5 months per year traveling. Eating out nonstop, cruising mostly in balcony cabins on mid-tier cruise ships with some upgrades. Airbnbs and hotels – we book a lot nicer places than we used to if we’re spending more than 8-10 hours in the accommodations (still do cheapo hotels sometimes for pre-cruise or airport layover hotels).
I don’t worry about time running out. I figure I’ll leave an inheritance but trying to spend it all and die with zero just seems stressful. Would rather devote my time to other things besides trying really hard to spend more money!
While I don’t agree with everything in the “Die with zero” book, one thing I took away is the authors idea of giving a pre-inheritance to your kids in their late 20s for a down payment on their first house. Their argument was giving a much smaller ammount earlier in their life makes a more life changing impact than waiting to get a larger in their 60s. If you wait to pass it down when you die, they will have lived their whole lives assuming that they won’t be receiving anything and may way over shoot and not be able to spend much of it in their lifetime.
I’m planning on giving some of my excesses towards matching my kids retirement contributions and home down payment funds in their 20s to help encourage and jump-start their FI journey.
It’s an interesting idea and something that I have thought about. No real plans to give large gifts to the kids any time soon (like six figure gifts). Back when planning for FIRE I had penciled in $15,000 per kid for down payment assistance, wedding costs, etc. After inflation that’s probably $30,000 in today’s dollars.
But on the kids’ current trajectory I’m hoping by their late 20’s they will be well on the way to FI themselves regardless of how much money I give to them. In the meantime, I’m hoping to continue some family travel to the extent possible while they are getting started in their careers (my treat). I have not read Die with Zero but I understand being generous by spending on experiences now, instead of later, is a key concept.
Its worth a read and has some different ways to think about splitting up spending and experiences at different life stages. For instance, backpacking around Europe in hostels is more fun in your 20s before kids than with kids later in life.
It was written from the perspective of someone who has tens of millions from a wallstreet career and wishes he spent more in his 20s, but not everyone will have that same experience.
If you reflect on your life would you rather inherited $60k in late 20s around when you bought your first house and were saving for FI or the equivalent ~$500k at age 60 invested 30+ years at 7% above inflation. The former gives you a lot more breathing room when need it the most vs when you’re already rich and don’t need more money.
Okay, I managed to read Die with Zero on the flight over to Amsterdam in September (and finish on the cruise). It was a little underwhelming and light on details/specific numbers. Cool concept but kind of niche (which he said he would be accused of being!).
I also see him having a much bigger problem spending all his money but he had another zero or two in his net worth compared to me. I’m at the “well I almost definitely have enough but I can’t just buy everything” stage. I did like the discussion on declining marginal utility and think I’m hitting that wall on some experiences. The first couple of British Isles cruises are incredibly awesome. We’ll see how the third one is next year and I’ll report back 🙂
Curious how June update is. Will you be posting soon? 😁
Working on it now! Unfortunately a series of vacations around the world kept me away from the keyboard for the last couple months 🙂
see we’re hanging on your every word Justin lol